Services

Tax Planning for Business Owners

The largest tax decisions in an owner's life are made years before the sale, and most of them cannot be undone at the letter of intent. We help owners and their CPAs make them early, then manage the proceeds when the day comes.

Last reviewed

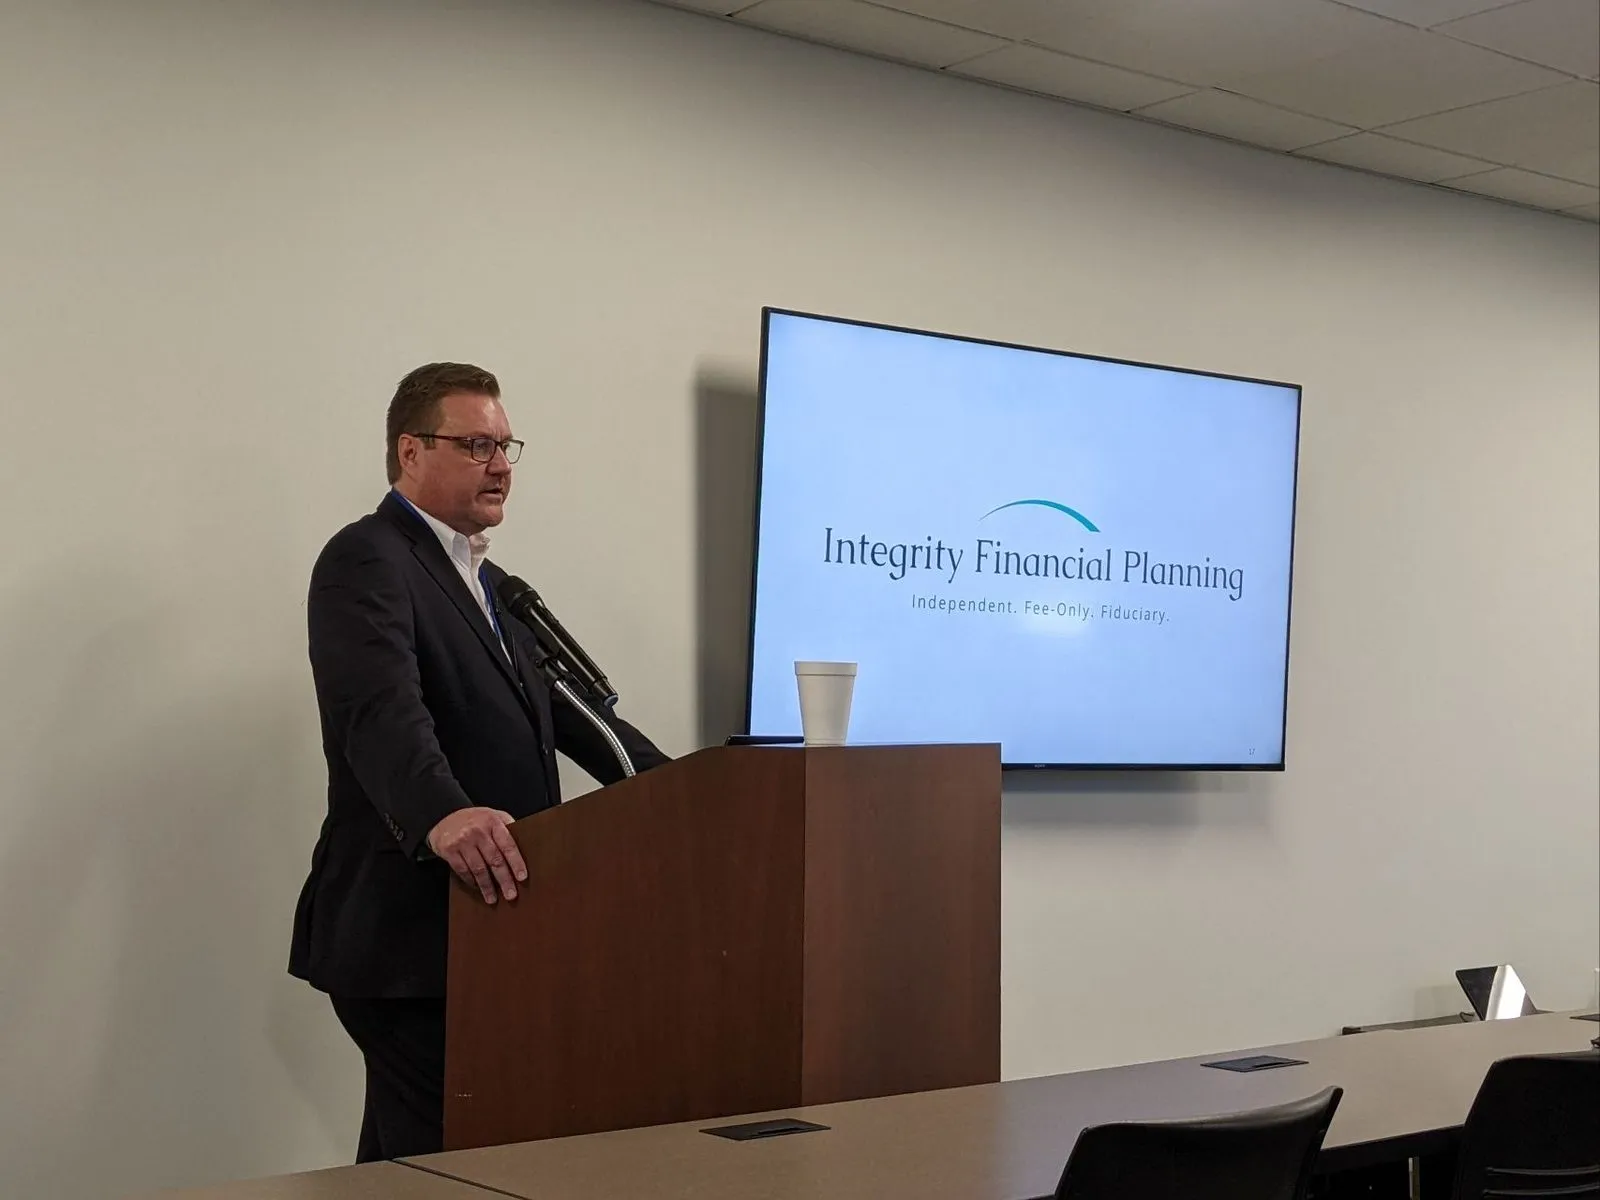
Todd Smurl presenting at a podium with the Integrity Financial Planning logo on screen

Who this is for

  • Founders and owners of closely held companies in Texas and Louisiana
  • Owners three to seven years from a possible sale, succession, or recapitalization
  • Physicians, dentists, attorneys, and other professionals with practice income who want six-figure retirement plan deductions
  • Owners whose net worth is concentrated in the business and who need a plan for everything outside it

Problems it solves

  • An S-corporation or LLC structure that forfeits the Section 1202 QSBS exclusion on a future sale
  • Depreciation, retirement plan, and entity decisions made one at a time by different advisors, without a view of the whole
  • A buy-sell agreement that was drafted once and never funded or updated
  • A tax return that is prepared every year but never planned

What makes it different

Ryan Firth is a CPA/PFS and CFP® professional who presents on advanced planning to Houston CPAs, so recommendations arrive in language your tax preparer can implement. We are not a CPA firm and do not prepare returns; we coordinate with your CPA and attorney rather than compete with them, and we are paid only by you.

Where we add the most value

Entity and exit structure

C-corporation versus S-corporation, the Section 1202 QSBS exclusion and its holding-period clock, installment sales, and rollover equity. For stock issued after July 4, 2025, QSBS can exclude up to $15 million of federal gain per issuer, with partial exclusions after three and four years; older stock keeps the $10 million cap and the five-year all-or-nothing rule. The decision has to be made years ahead, which is why we start here.

Retirement plan design

401(k) with profit sharing, cash balance plans, and the trade-off between owner deductions and employee cost. For an owner in their 50s with stable profits, a cash balance plan layered on a 401(k) can turn a six-figure tax bill into a six-figure retirement contribution.

Depreciation and real estate

Whether to hold real estate inside or outside the operating company, when a cost segregation study pays for itself under 100% bonus depreciation, and how depreciation recapture affects a later sale. See Is cost segregation still worth it?

Risk and insurance structure

Buy-sell agreement funding, key-person coverage, and when a captive insurance arrangement is worth its complexity. We do not sell insurance, so the recommendation is only about whether you need it.

Concentration and the years before a sale

Diversifying outside the business in a Personal Index Portfolio managed within a written tax budget, pre-sale gifting and estate moves that work better before a valuation jump, and a plan for the proceeds so a liquidity event does not become a tax event twice.

How an engagement runs

  1. Discovery. We read the returns, the operating agreement, the buy-sell, and the retirement plan documents, and we talk with your CPA.
  2. Analysis. We model the alternatives with your numbers: entity change or not, plan design, depreciation timing, sale structures.
  3. Written recommendations. A plan your CPA and attorney can implement, with the trade-offs stated plainly.
  4. Implementation and follow-through. We coordinate the professionals, track deadlines, and revisit the planning as the business and the law change.

Case studies and reading

Ready to start early? Schedule a meeting or ask your CPA to reach us through our CPA Partners page.

Questions about tax planning for business owners

Do you prepare tax returns?

No. Integrity Financial Planning is a fee-only investment adviser, not a CPA firm. We do the forward-looking planning and hand your CPA a written set of recommendations to implement on the return. If you do not have a CPA, we can introduce you to one.

How is tax planning for business owners charged?

Tax planning is part of financial planning, which is included in the investment management fee for clients whose portfolios we manage. There is no separate planning charge. See our fees.

Can an S-corporation qualify for QSBS?

No. Section 1202 applies only to original-issue stock of a domestic C-corporation. Owners who expect a large sale should evaluate converting well before an exit; the holding period starts when the C-corporation stock is issued. Our QSBS guide covers the 2025 changes.

What is a cash balance plan?

A defined-benefit retirement plan that allows much larger tax-deductible contributions than a 401(k) alone, often six figures per year for owners in their 50s and 60s. It comes with actuarial costs and a commitment to fund employees, so it fits stable, high-income businesses.

When does a cost segregation study make sense?

When you own or are buying commercial or rental real estate through the business and can use large first-year deductions. With 100% bonus depreciation restored for property acquired after January 19, 2025, a study can move a large share of the purchase price into the first year. We model whether the deduction is worth more to you now or spread over time. Read our analysis.

Do you work with my existing CPA and attorney?

Yes, and we prefer it. Most engagements involve a shared call with your CPA early on and coordination with counsel on entity and buy-sell work. See our CPA Partners page.

Talk with a CFA and a CPA/PFS, CFP® about your situation

A free introductory meeting, no obligation. Financial planning is included as part of the investment management fee, so there is no separate planning charge.