Is Cost Segregation Still Worth It Now That 100% Bonus Depreciation Is Back?
The 2025 tax law made 100% bonus depreciation permanent for property acquired after January 19, 2025. What that means for cost segregation, and why the recapture math still decides whether a study pays.

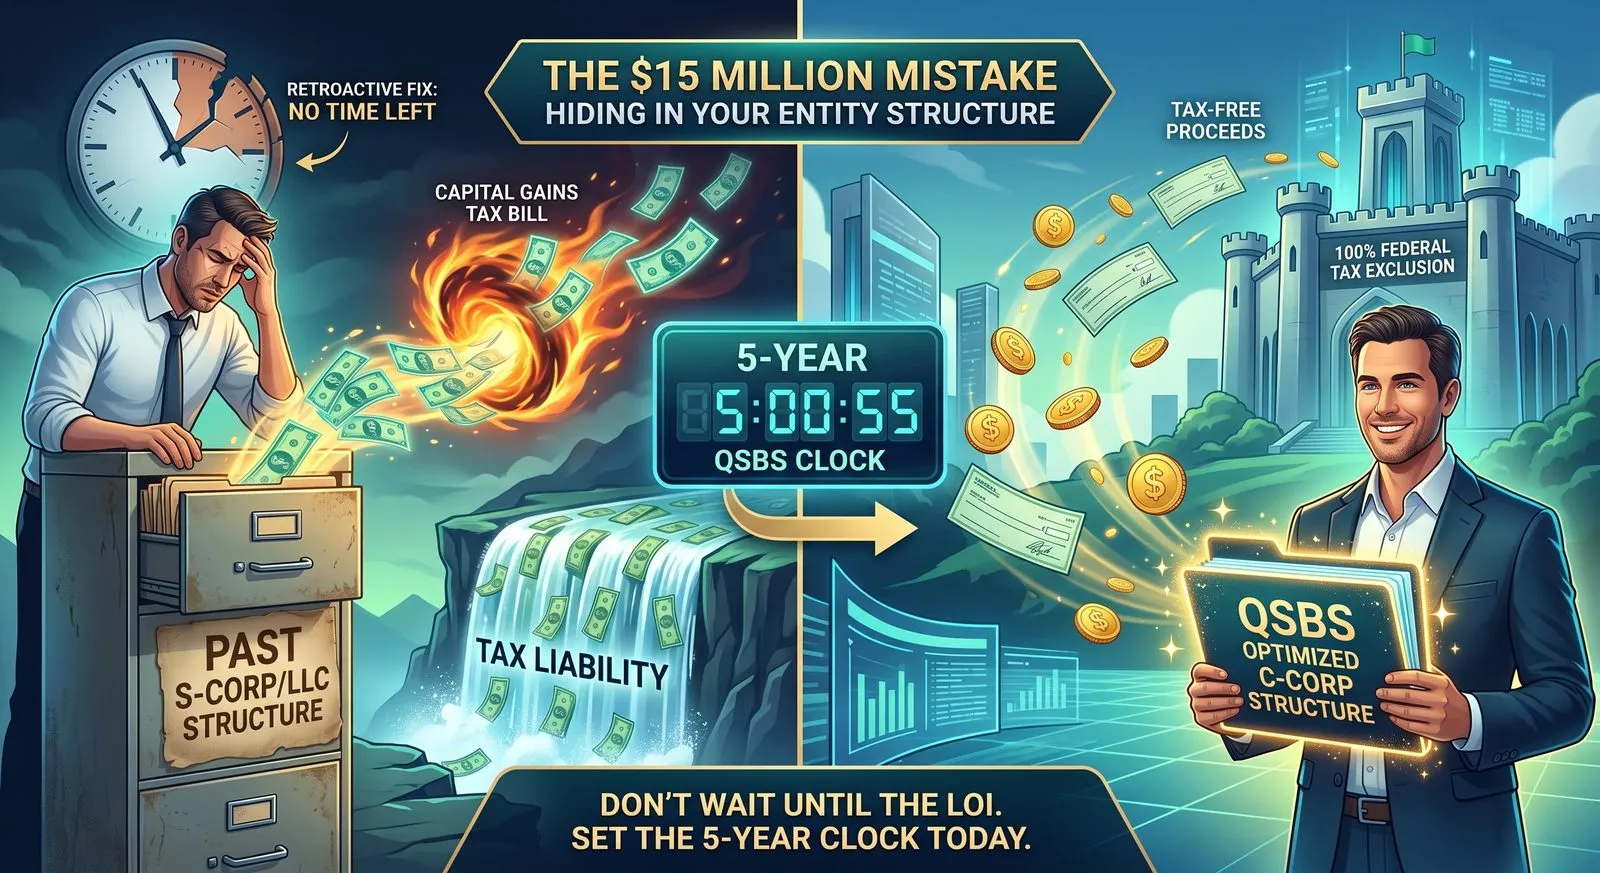
Bottom Line Up Front: Yes. Cost segregation is more valuable now than it has been since 2022, because the One Big Beautiful Bill Act (OBBBA) made 100% bonus depreciation permanent for property acquired after January 19, 2025. But a bigger first-year deduction also means a bigger "recapture" bill when you sell. If your tax professional chases the upfront write-off without modeling the exit, the strategy can still cost you money. Treat cost segregation as a long-term wealth decision, not a quick deduction.
For a few years, real estate investors watched the best depreciation rules in decades slip away. Under the 2017 tax law, 100% bonus depreciation began phasing down after 2022: 80% in 2023, 60% in 2024, 40% in 2025, on its way to zero. Many investors, and some tax professionals, concluded that cost segregation studies were no longer worth the engineering fee.
That conclusion was wrong then, and the law has since changed underneath it.
What Did the 2025 Tax Law Change?
The OBBBA, signed on July 4, 2025, permanently restored 100% bonus depreciation for qualified property that is both acquired and placed in service after January 19, 2025. There is no scheduled phase-down. For real estate investors, that means every building component a cost segregation study identifies with a recovery period of 20 years or less (carpet, cabinetry, dedicated electrical, parking lots, landscaping, and similar items) can be written off in full in the year the property is placed in service.
Two details matter:
- The acquisition date controls. Property acquired on or before January 19, 2025 remains under the old rules even if it is placed in service later: 40% bonus in 2025, 20% in 2026, and none from 2027. A binding contract signed before January 20, 2025 generally fixes the acquisition date.
- A new category for manufacturers. The law also allows 100% depreciation for "qualified production property," the nonresidential real property itself when it is used in manufacturing, production, or refining, provided construction begins after January 19, 2025 and before 2029 and the property is placed in service before 2031. That is a separate election with its own rules, but it can be combined with a cost segregation study on the same facility.
How Does Cost Segregation Work?
Without a study, a commercial building is depreciated straight-line over 39 years (27.5 years for residential rental property). A cost segregation study, performed by an engineering firm, breaks the purchase price into components and assigns each its correct recovery period: 5-year personal property, 7-year property, 15-year land improvements, and the 39-year building shell.
With 100% bonus depreciation, everything in the 5-, 7-, and 15-year buckets can be deducted immediately. On a typical commercial property, 20% to 35% of the purchase price falls into those buckets; on certain property types, such as restaurants, medical offices, and hotels, it can be more. A $4 million acquisition might produce a first-year deduction of $1 million or more instead of roughly $80,000 to $100,000 under straight-line.
Even when bonus depreciation was fading, accelerating deductions from 39 years to 5, 7, or 15 remained a net-present-value win. A dollar of deduction today is worth more than the same dollar spread over four decades. With 100% bonus back, the first-year cash flow is simply larger.
What Is the "Recapture Trap" (and Why Should You Care)?
Accelerated depreciation is a timing benefit, not a permanent one. When you sell, the IRS wants it back, and the rate depends on the type of property:
- 5- and 7-year components (Section 1245 property) are recaptured as ordinary income, at rates up to 37%, to the extent of the gain.
- Straight-line depreciation on the building (Section 1250 property) is taxed as "unrecaptured Section 1250 gain" at a maximum rate of 25%.
- Any remaining gain is taxed at long-term capital gains rates, currently up to 20% plus the 3.8% net investment income tax.
Because 100% bonus depreciation front-loads the entire deduction, the ordinary-income recapture on a short hold is now larger than it would have been under the phase-down. If you sell in two or three years, the tax owed at the exit can wipe out most of what you saved going in. A Section 1031 exchange can defer the recapture along with the rest of the gain, but only if the exit is planned that way from the start.
Can You Actually Use the Deduction?
A large first-year loss is only valuable if it offsets income you would otherwise pay tax on. Three rules decide that:
- Passive activity rules. Rental losses are passive unless you qualify as a real estate professional (more than 750 hours and more than half your working time in real property trades) or the property is a short-term rental you materially participate in. Passive losses that cannot be used carry forward.
- Excess business loss limitation. Even for active taxpayers, the amount of business loss that can offset wages and portfolio income in a single year is capped (indexed annually); the excess becomes a net operating loss carried forward.
- State conformity. Several states do not follow federal bonus depreciation, so the state benefit may be smaller or arrive over time.
How Do You Protect Your Wealth Before Ordering a Study?
Cost segregation is a powerful tool, but it is fundamentally a long-term hold strategy. You should never order an engineering study without doing the financial math first.
At Integrity Financial Planning, we run a comprehensive ROI analysis before you engage a firm to do the study. We calculate three non-negotiable metrics:
- The upfront tax savings: how much cash flow you will free up in the current tax year, after the passive-loss and excess-business-loss limits.
- The future recapture hit: a clear projection of what you will owe upon selling the property, split between ordinary-rate and 25%-rate recapture.
- The break-even holding period: the number of years you must hold the property for the strategy to be profitable, and how a 1031 exchange changes it.
Ready to Run the Numbers?
Do not just buy a tax deduction; make sure the math supports your long-term wealth goals. If you are acquiring commercial or rental real estate, or bought property after January 19, 2025, you have a larger opportunity than investors did a year ago, and a larger exit liability to plan around.
Schedule a meeting with the team at Integrity Financial Planning to run a break-even analysis on your properties before you file your next return.
This material is intended for informational and educational purposes only and should not be construed as tax, legal, or investment advice. Depreciation rules depend on the specific property, acquisition date, and taxpayer; consult your tax professional before acting.
Sources: One Big Beautiful Bill Act: 100% Bonus Depreciation and Qualified Production Property (BDO); IRS Publication 946, How to Depreciate Property; OBBBA Tax Provisions (Mayer Brown).
Frequently asked questions
Is 100% bonus depreciation permanent?
Yes. The One Big Beautiful Bill Act, signed July 4, 2025, restored 100% bonus depreciation for qualified property acquired and placed in service after January 19, 2025, with no scheduled phase-down.
What if I bought the property before January 20, 2025?
Property acquired on or before January 19, 2025 stays under the prior phase-down: 40% bonus if placed in service in 2025, 20% in 2026, and none after that. Cost segregation still accelerates the remaining depreciation, but the first-year benefit is smaller.
Does cost segregation make sense if I plan to sell within a few years?
Usually not. Accelerated depreciation on 5- and 7-year components is recaptured at ordinary income rates when you sell, so a short holding period can hand most of the benefit back. A 1031 exchange can defer the recapture, but the analysis should be done before the study is ordered.
Get our insights by email
Occasional notes on planning, portfolios, and taxes. Unsubscribe anytime.
This article is for general educational purposes and is not individualized tax, legal, or investment advice. Tax laws change; confirm how current rules apply to your situation before acting. See our disclosures.