The $15 Million Exit Mistake: How Section 1202 QSBS Eliminates Capital Gains Tax on a Business Sale
How Section 1202 QSBS can exclude up to $15 million of gain on a C-corporation sale, what the 2025 tax law changed (tiered 3-, 4-, and 5-year exclusions, $75 million asset cap), and why the clock must start years before an exit.

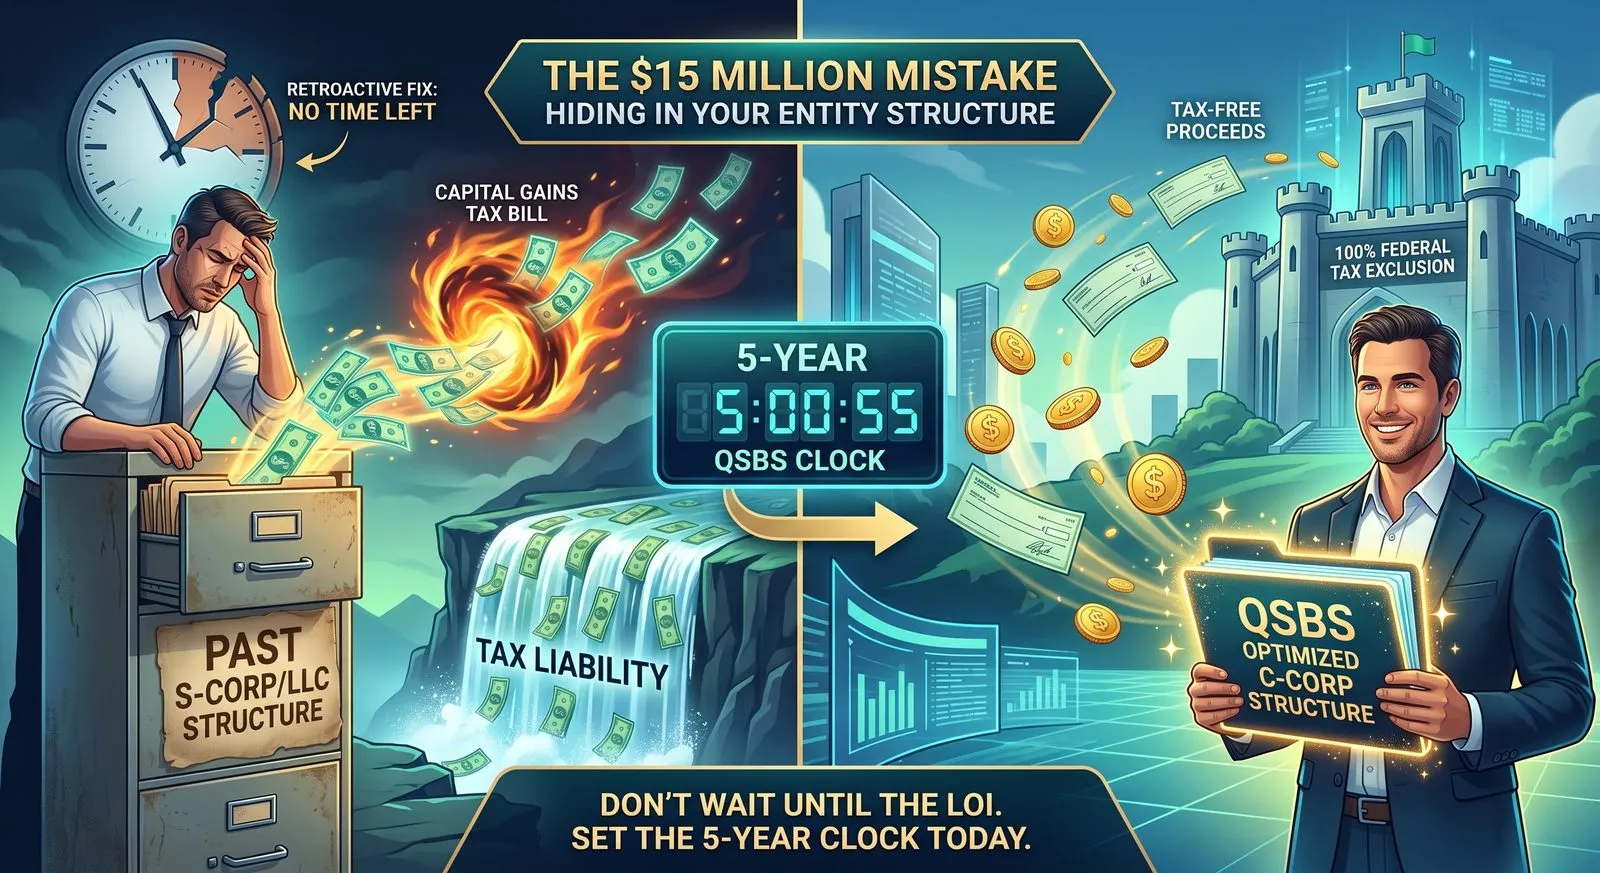
Under IRC Section 1202, Qualified Small Business Stock (QSBS) allows eligible founders and business owners to exclude up to 100% of federal capital gain—up to $15 million or 10 times their adjusted basis—when selling their company. To qualify for the full exclusion, you must hold original-issuance C-Corporation stock for at least five consecutive years. The One Big Beautiful Bill Act (OBBBA), signed July 4, 2025, added partial exclusions at three and four years for newly issued stock, but the five-year mark remains the goal.
Every year, successful business owners sign a Letter of Intent (LOI) to sell their company for up to $15 million, only to face an unexpected reality: a federal capital gains tax bill exceeding $3.5 million.
When you discover this tax liability during the transaction, it is already too late. Tax planning is never retroactive. If your company’s entity structure is reviewed and optimized five years prior to an exit, that entire federal capital gains liability could legally drop to zero.
What Is Section 1202 Qualified Small Business Stock (QSBS)?
Internal Revenue Code (IRC) Section 1202 was enacted by Congress to incentivize long-term investment in American operating businesses. It permits non-corporate shareholders to exclude up to 100% of the federal capital gains realized on the sale of Qualified Small Business Stock.
To qualify for the complete federal exemption, your business must satisfy several statutory criteria:
- Eligible Entity Type: The business must be an active domestic C-Corporation.
- Original Issuance: You must acquire the shares directly from the corporation in exchange for money, property, or services—not via secondary purchase from another shareholder.
- Gross Asset Cap: The company’s aggregate gross assets must not exceed $75 million at any time before or immediately following the stock issuance (indexed for inflation from 2027). For stock issued on or before July 4, 2025, the limit is $50 million.
- Active Business Requirement: At least 80% of corporate assets must be used in the active conduct of a qualified trade or business (excluding personal services like law, healthcare, hospitality, and finance).
Can an S-Corporation Qualify for QSBS?
No. An S-Corporation cannot issue Qualified Small Business Stock. QSBS treatment is strictly reserved for domestic C-Corporations.
Many small business CPAs default to recommending S-Corporation status to avoid corporate-level taxation on ongoing operational profits. While this saves income taxes in the early operating phase, it creates an enormous structural penalty when you build a high-valuation company. Staying structured as an S-Corporation forfeits your eligibility for the 100% Section 1202 capital gains exclusion upon sale.
What Did the 2025 Tax Law Change?
The OBBBA made Section 1202 more generous for stock issued after July 4, 2025. Three changes matter to a founder planning an exit:
| Rule | Stock issued on or before July 4, 2025 | Stock issued after July 4, 2025 |
|---|---|---|
| Holding period and exclusion | 5 years for 100%; nothing before that | 3 years: 50%. 4 years: 75%. 5 years: 100% |
| Per-issuer cap (or 10x basis, if greater) | $10 million | $15 million, indexed for inflation from 2027 |
| Gross-asset limit at issuance | $50 million | $75 million, indexed from 2027 |
Two cautions. First, the issue date controls, not the sale date: shares you already hold stay under the old rules, and only new issuances (including stock received when an LLC or S-Corporation converts after July 4, 2025) get the new ones. Second, the partial tiers are less generous than they look. The portion of gain that is not excluded is taxed at a maximum federal rate of 28% plus the 3.8% net investment income tax, not the 20% long-term rate. On a $15 million gain, a three-year exit under the 50% tier still leaves roughly $2.4 million of federal tax; a four-year exit under the 75% tier leaves about $1.2 million; five years leaves zero.
When Does the QSBS Holding Period Need to Start?
The holding clock begins on the precise day your C-Corporation issues your stock—not the day you originally founded an LLC, sole proprietorship, or S-Corporation.
If you anticipate selling your enterprise in 2031, your entity restructuring and share issuance must be completed immediately to reach the five-year, 100% tier; a 2029 or 2030 exit on stock issued now would land in the 50% or 75% tiers. Once an acquirer submits a Letter of Intent (LOI), your corporate structure is locked. There is no legal election, retroactive filing, or accounting workaround that can start the QSBS clock in the middle of a sale.
How Much Capital Gains Tax Can You Save With QSBS?
Evaluating a $15 million business sale with a minimal cost basis demonstrates the stark financial contrast between a traditional pass-through entity exit and a QSBS-optimized exit:
Traditional Pass-Through / S-Corp Sale
Entity Type: S-Corporation or LLC
- Mandatory Holding Period: 1+ Year (Standard Long-Term)
- Federal Capital Gains Tax: 20.0%
- Net Investment Income Tax (NIIT): 3.8%
- Federal Tax Due on a $15M Gain: ~$3,570,000
- Net After-Tax Proceeds Retained: ~$11,430,000
Section 1202 QSBS C-Corp Sale
- Entity Type: Domestic C-Corporation
- Holding Period: 5 Consecutive Years (100% tier; 3 and 4 years qualify for 50% and 75% on post-July 4, 2025 stock)
- Federal Capital Gains Tax: 0.0% (100% Exclusion)
- Net Investment Income Tax (NIIT): 0.0%
- Federal Tax Due on a $15M Gain: $0.00 (Within statutory caps)
- Net After-Tax Proceeds Retained: ~$15,000,000
The Net Difference
Setting the five-year clock and meeting QSBS requirements saves an estimated $3,570,000 in federal taxes on a $15 million sale, keeping 100% of those proceeds with the business owner. Under the new tiers, the same sale after four years would save roughly $2.4 million and after three years roughly $1.2 million, because the non-excluded half or quarter is taxed at 28% plus NIIT.
Note: State tax implications vary by jurisdiction. Certain states follow federal Section 1202 guidelines, while others (such as California) do not conform.
Frequently Asked Questions About Section 1202 QSBS
Can I convert my existing S-Corp or LLC to a C-Corp to claim QSBS?
Yes. An operating LLC or S-Corporation can convert into a C-Corporation to initiate the five-year QSBS holding period for future business growth. However, any unrealized gain accrued prior to the conversion date remains subject to standard capital gains taxes; only the incremental appreciation that occurs after the conversion date qualifies for the Section 1202 exclusion.
What happens if I sell my business before the 5-year holding period expires?
For stock issued after July 4, 2025, you can still exclude 50% of the gain after three years or 75% after four, with the remainder taxed at up to 28% plus NIIT. For stock issued earlier, selling before five years forfeits the exclusion entirely. In either case, under IRC Section 1045, you can roll over the proceeds tax-deferred into replacement QSBS stock of another active company within 60 days of the sale, preserving your long-term tax deferral.
What is the maximum dollar gain exclusion permitted under Section 1202?
For stock issued after July 4, 2025, the maximum federal gain exclusion per taxpayer, per issuer is the greater of $15 million (indexed for inflation beginning in 2027) or 10 times your adjusted tax basis in the stock. For stock acquired between September 28, 2010 and July 4, 2025, the flat cap is $10 million. Through advanced estate and trust structuring ("QSBS stacking"), founders can often multiply this exclusion across multiple non-grantor trusts to shield $30 million or more in gain.
Can I fix my entity structure after an acquisition offer or LOI arrives?
No. Restructuring equity or making entity conversions after a Letter of Intent has been executed violates the economic substance doctrine and will be invalidated during an IRS audit. Structuring for Section 1202 must occur well before go-to-market discussions take place.
Build Your Tax Moat with Integrity Financial Planning
Routine compliance accounting only documents the past—filing returns to tally what you already owe. Strategic wealth management engineers the future.
Ryan Firth, CPA/PFS, CFP®, Head of Planning at Integrity Financial Planning, collaborates directly with business owners and entrepreneurs to build tax-efficient exit plans years before an acquisition takes place.
If you are planning an exit within the next 3 to 7 years, every month of delay narrows your planning window.
Schedule an entity structure review with Integrity Financial Planning today to determine whether your business qualifies for Section 1202 and protect your wealth before you exit.
Sources (verified September 28, 2026): 26 U.S.C. § 1202, Partial exclusion for gain from certain small business stock (Legal Information Institute, current text including the 2025 amendments); Tax Provisions in P.L. 119-21, the FY2025 Reconciliation Law (Congressional Research Service, July 2025); QSBS Gets a Makeover: What Tax Pros Need to Know About Sec. 1202's New Look (The Tax Adviser, November 2025); The One Big Beautiful Bill Act Expands QSBS Benefits (Cooley, July 11, 2025); Understanding the QSBS Tax Exclusion (Northern Trust, October 2025).
Frequently asked questions
What did the One Big Beautiful Bill Act change for QSBS?
For stock issued after July 4, 2025: a tiered exclusion of 50% after three years, 75% after four, and 100% after five; a higher per-issuer cap of $15 million (up from $10 million), indexed for inflation from 2027; and a gross-asset limit of $75 million (up from $50 million). Stock issued on or before July 4, 2025 remains under the old rules.
Is the partially excluded gain taxed at normal capital gains rates?
No. The portion of QSBS gain that is not excluded under the 50% or 75% tiers is taxed at a maximum federal rate of 28% plus the 3.8% net investment income tax, rather than the 20% long-term rate. The tiers are valuable, but the five-year, 100% exclusion is still the target.
Get our insights by email
Occasional notes on planning, portfolios, and taxes. Unsubscribe anytime.
This article is for general educational purposes and is not individualized tax, legal, or investment advice. Tax laws change; confirm how current rules apply to your situation before acting. See our disclosures.