Case Study: How a Simple Business Pivot Almost Cost a Tech Founder $2.4M in Taxes
A Houston SaaS founder nearly lost a $10 million QSBS exclusion by pivoting into data hosting two years before his exit. How the active-business test works, what the 2025 tax law changed, and what saved $2.4 million.

Bottom Line Up Front: A single change in your business model—like signing a new lease or offering a new service—can accidentally disqualify you from a life-changing tax exemption under Section 1202 (QSBS). Here is how continuous financial advisory saved one SaaS founder from losing a $10 million tax-free gain.
As a successful founder, you are always looking for ways to adapt, expand, and grow your business. But when you are marching toward an eventual exit, every strategic pivot comes with massive financial implications.
Recently, the team at Integrity Financial Planning worked with a Houston-based SaaS founder who was roughly two years away from a major exit. What started as an exciting expansion plan almost turned into a multi-million-dollar tax disaster.
Here is why proactive planning is non-negotiable.
What is the Section 1202 (QSBS) Tax Exemption?
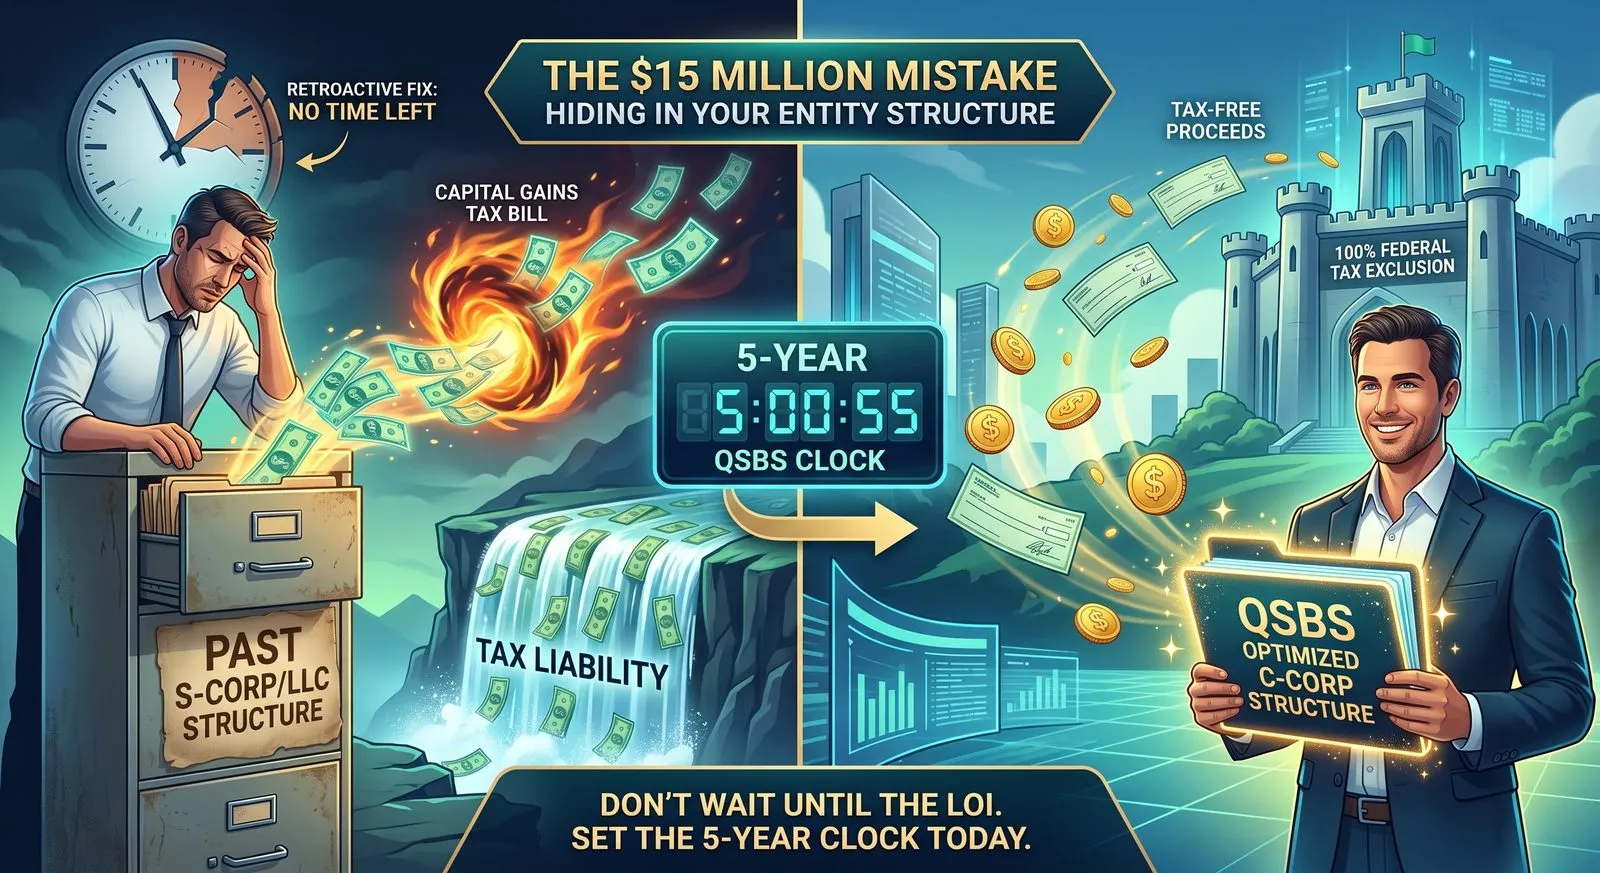
For startup founders and early investors, Section 1202 of the IRS code—often referred to as the Qualified Small Business Stock (QSBS) exemption—is one of the most powerful wealth-building tools in existence. If you meet the strict criteria, it allows you to exclude up to $10 million (or potentially more) of your capital gains from federal taxes when you sell your company.
Our client had some good news: his company was a C-Corp, and he had held the stock for four years. However, because his shares were issued before the One Big Beautiful Bill Act (OBBBA) was signed on July 4, 2025, none of that law's improvements applied to him. The $15 million cap, the $75 million gross-asset limit, and the new partial exclusions (50% after three years, 75% after four) are available only for stock issued after that date. He was firmly locked into the traditional rules: a $10 million cap and a five-year, all-or-nothing holding period.
This meant we had absolutely zero margin for error. There was no 75% fallback tier if something went wrong in year five; we needed to protect every single cent of that $10 million limit. (For a full breakdown of the old and new rules, see our guide to Section 1202 QSBS and the 2025 tax law.)
The Hidden Trap: How Can a Pivot Disqualify You?
The danger arose when the founder decided to expand his operations. He was preparing to sign a lease for a massive server farm, effectively pivoting a portion of his SaaS business model into "data hosting."
From a business growth perspective, it made sense. From a tax perspective, it was a ticking time bomb.
Section 1202 (QSBS) has strict rules about what qualifies as an "active trade or business." At least 80% of the corporation's assets, by value, must be used in qualified activities for substantially all of the holding period. The statute excludes businesses where the principal asset is the reputation or skill of employees, professional services such as law, health, and financial services, hospitality, and businesses whose assets are mainly real estate or investment holdings. Those rules were not changed by the 2025 law.
By pivoting heavily into data hosting and server leasing, the company was drifting dangerously close to being classified as a "passive" asset-holding entity rather than an active SaaS trade. If the IRS reclassified the business, the founder would lose his entire QSBS exemption—costing him roughly $2.4 million in unexpected federal tax upon exit ($10 million of gain at the 20% long-term capital gains rate plus the 3.8% net investment income tax).
How Proactive Advisory Saved the Day
Tax compliance is about looking backward at what happened last year. True wealth management is about looking forward at what you are about to do.
Because this founder was in a Continuous Advisory relationship with us, we didn't find out about the new server farm after the lease was already signed. We caught the pivot during the planning phase.
Before any ink was dry, our team stepped in and executed a three-step intervention:
- We restructured the expansion: We adjusted the operational strategy to ensure the primary revenue drivers remained firmly within the bounds of qualified SaaS activities.
- We documented the "Active Business" test: We built a paper trail in real-time, proactively gathering the exact documentation needed to withstand future IRS scrutiny.
- We safeguarded the exclusion: We locked in the strategy so the founder could confidently proceed toward his exit.
The Result: A Life-Changing Exit
Two years later, the client successfully sold his company.
The result? A $10 million gain with $0 in federal tax. Even without access to the newer $15 million limit, walking away with $10 million completely tax-free is a life-changing financial victory.
For founders whose stock is issued after July 4, 2025, the same discipline matters even more: the potential exclusion is 50% larger, and while the tiered holding periods soften the cliff for an early sale, the active-business test is just as unforgiving.
Don't Make Major Moves in the Dark
If you are planning to expand your footprint, launch a new service line, or restructure your operations, do not wait until tax season to tell your financial advisor. The rules surrounding QSBS and capital gains are rigid, and innocent business decisions can easily trigger massive tax liabilities.
Are you an entrepreneur or business owner preparing for an exit? Before you make your next major strategic pivot, schedule a meeting with Integrity Financial Planning. Let our continuous advisory team review the math and protect your wealth before you sign on the dotted line.
This material is for informational and educational purposes only and should not be construed as tax, legal, or investment advice.
Sources (verified September 28, 2026): 26 U.S.C. § 1202, Partial exclusion for gain from certain small business stock (Legal Information Institute, current text including the 2025 amendments); Tax Provisions in P.L. 119-21, the FY2025 Reconciliation Law (Congressional Research Service, July 2025); The One Big Beautiful Bill Act Expands QSBS Benefits (Cooley, July 11, 2025); Understanding the QSBS Tax Exclusion (Northern Trust, October 2025).
Frequently asked questions
Why didn't the founder qualify for the $15 million QSBS cap?
The higher $15 million cap, the $75 million gross-asset limit, and the tiered 3-, 4-, and 5-year exclusions in the One Big Beautiful Bill Act apply only to stock issued after July 4, 2025. His shares were issued years earlier, so the prior rules governed: a $10 million cap and a strict five-year, all-or-nothing holding period.
How can a business pivot disqualify QSBS?
Section 1202 requires that at least 80% of the corporation's assets be used in the active conduct of a qualified trade or business throughout the holding period. Shifting substantial assets into real estate leasing, data-center infrastructure held for rent, or other passive or excluded activities can fail that test for the affected years.
Would the outcome differ for a founder whose stock was issued after July 4, 2025?
The stakes would be larger and the cliff less steep. The cap rises to $15 million, and a sale after three or four years still excludes 50% or 75% of the gain, with the remainder taxed at up to 28% plus 3.8% NIIT. The active-business requirement is unchanged, so a disqualifying pivot would still forfeit the exclusion.
Get our insights by email
Occasional notes on planning, portfolios, and taxes. Unsubscribe anytime.
This article is for general educational purposes and is not individualized tax, legal, or investment advice. Tax laws change; confirm how current rules apply to your situation before acting. See our disclosures.