The Maturation of Wealth: Transitioning Your Portfolio for the Distribution Phase
Why Houston energy executives outgrow brokerage platforms near retirement: fewer fee layers, active cash management, and tax-aware retirement income.

At Integrity Financial Planning, we believe a truly rich life is defined by the journey and your personal satisfaction, not by a specific number on a balance sheet. During your career's wealth accumulation phase, institutional brokerage models and corporate 401(k) platforms likely served you well.
Why do executives move to a fee-only fiduciary near retirement?
As retirement nears, many executives find their finances have outgrown a brokerage platform. Concentrated stock, deferred compensation, and the shift from saving to withdrawing call for coordinated tax and income planning. A fee-only fiduciary is paid only by clients, takes no commissions, and is required to act in your best interest.
As a Houston energy executive or engineering director looking toward retirement, you will likely find your financial life growing more complex. Moving into the distribution phase often means handling concentrated employer stock and non-qualified deferred compensation (NQDC), and planning around the buyouts that come with the oil and gas cycle.
Outgrowing an institutional platform is a natural step as wealth matures. Managing multiple tax brackets and legacy accounts calls for a specialized approach with fewer conflicts of interest, one designed to reduce paperwork and simplify your financial life. Here is how moving to an independent, fee-only fiduciary can support the next chapter.
The mathematics of streamlined fees
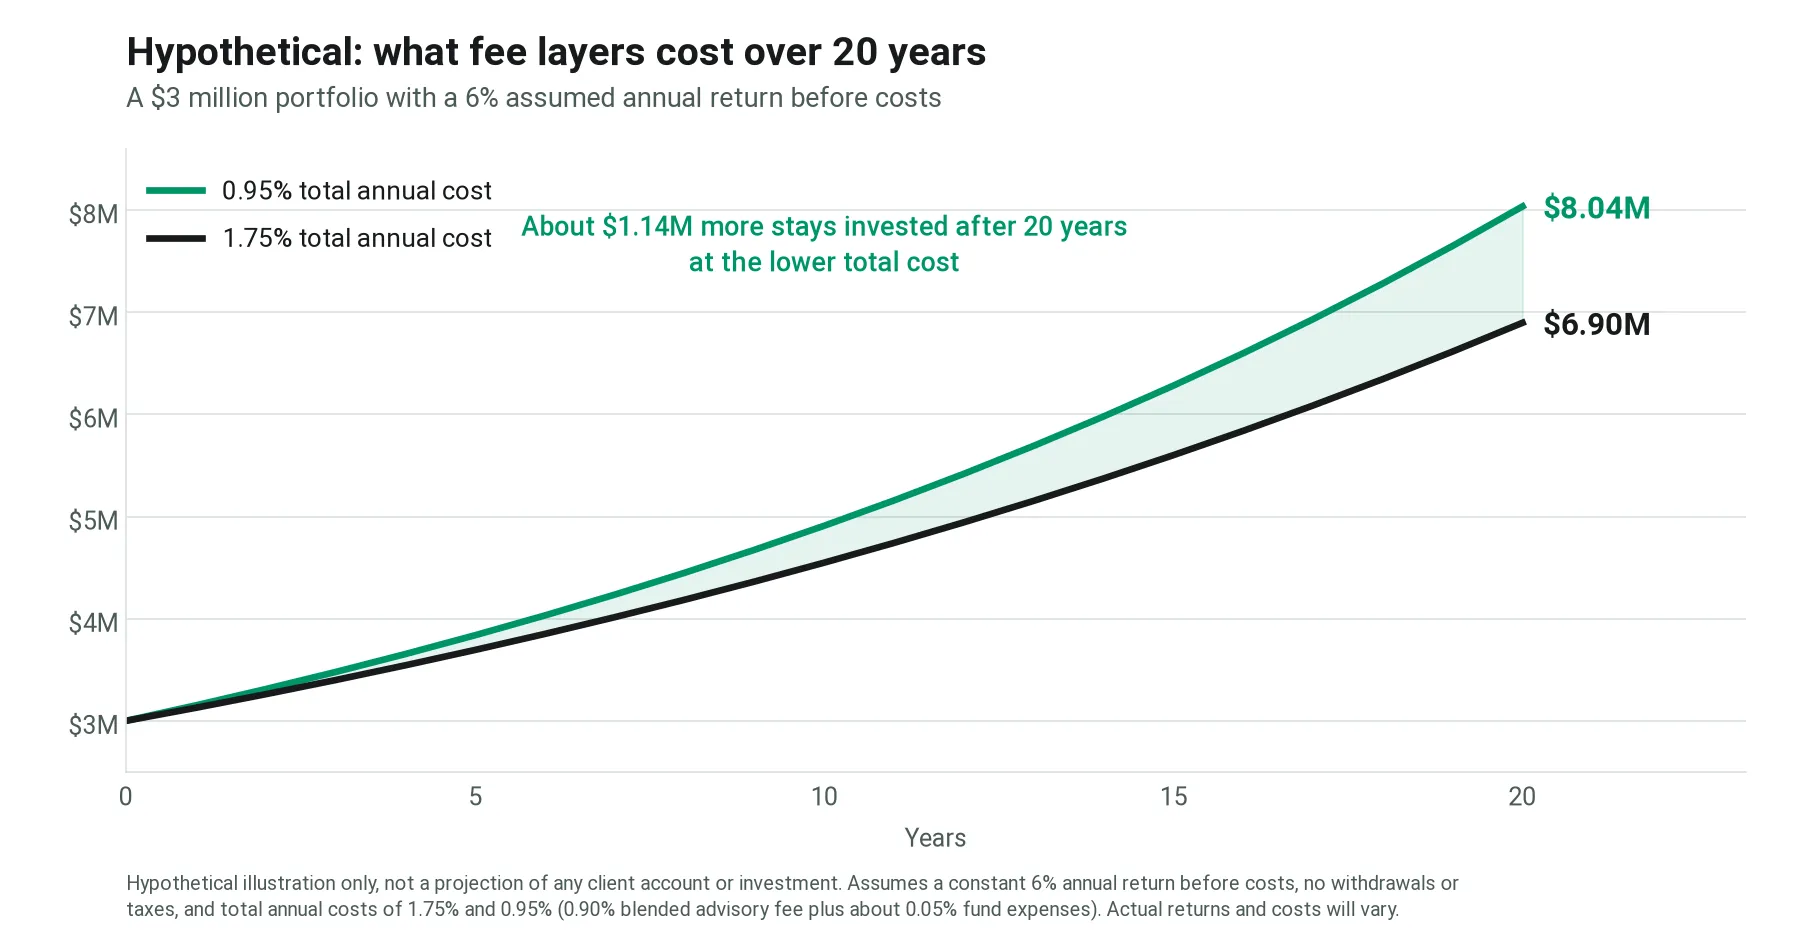
As portfolios grow, cost efficiency matters more. At a traditional brokerage, wrap fees, platform charges, and fund expense ratios can add up to roughly 1.5% to 2.0% a year. Wrap fees alone can range from 1% to 3% of assets, according to The Wall Street Journal, and fund expenses are usually charged on top.
We are a fee-only fiduciary: we accept no commissions and are paid only by our clients. Our fee schedule is published. We charge 1.0% per year on the first $1 million and 0.85% from $1 million to $10 million. On a $3 million portfolio, that works out to a blended 0.90%. Because our portfolios are built from low-cost ETFs, the internal expense ratio of an all-ETF portfolio is a little under 5 basis points (0.05%).
Over long periods, removing avoidable fee layers keeps more capital invested and compounding, though market returns and your net results will still vary.
A more careful approach to cash management
Good portfolio management includes managing your cash. In January 2025, the SEC settled charges against Wells Fargo Advisors and Merrill Lynch for failing to adopt policies that considered advisory clients' best interests when offering cash sweep options, according to the SEC. The firms paid $60 million in combined penalties. During periods of rising rates, the gap between their bank sweep yields and other cash options at times grew to almost 4%.
As an independent fiduciary, we are required to act in your best interest. We actively manage your cash, using appropriate higher-yielding money market options where they fit, so your cash reserves work efficiently within your broader portfolio.
Tax drag vs. tax alpha with Personal Index Portfolios
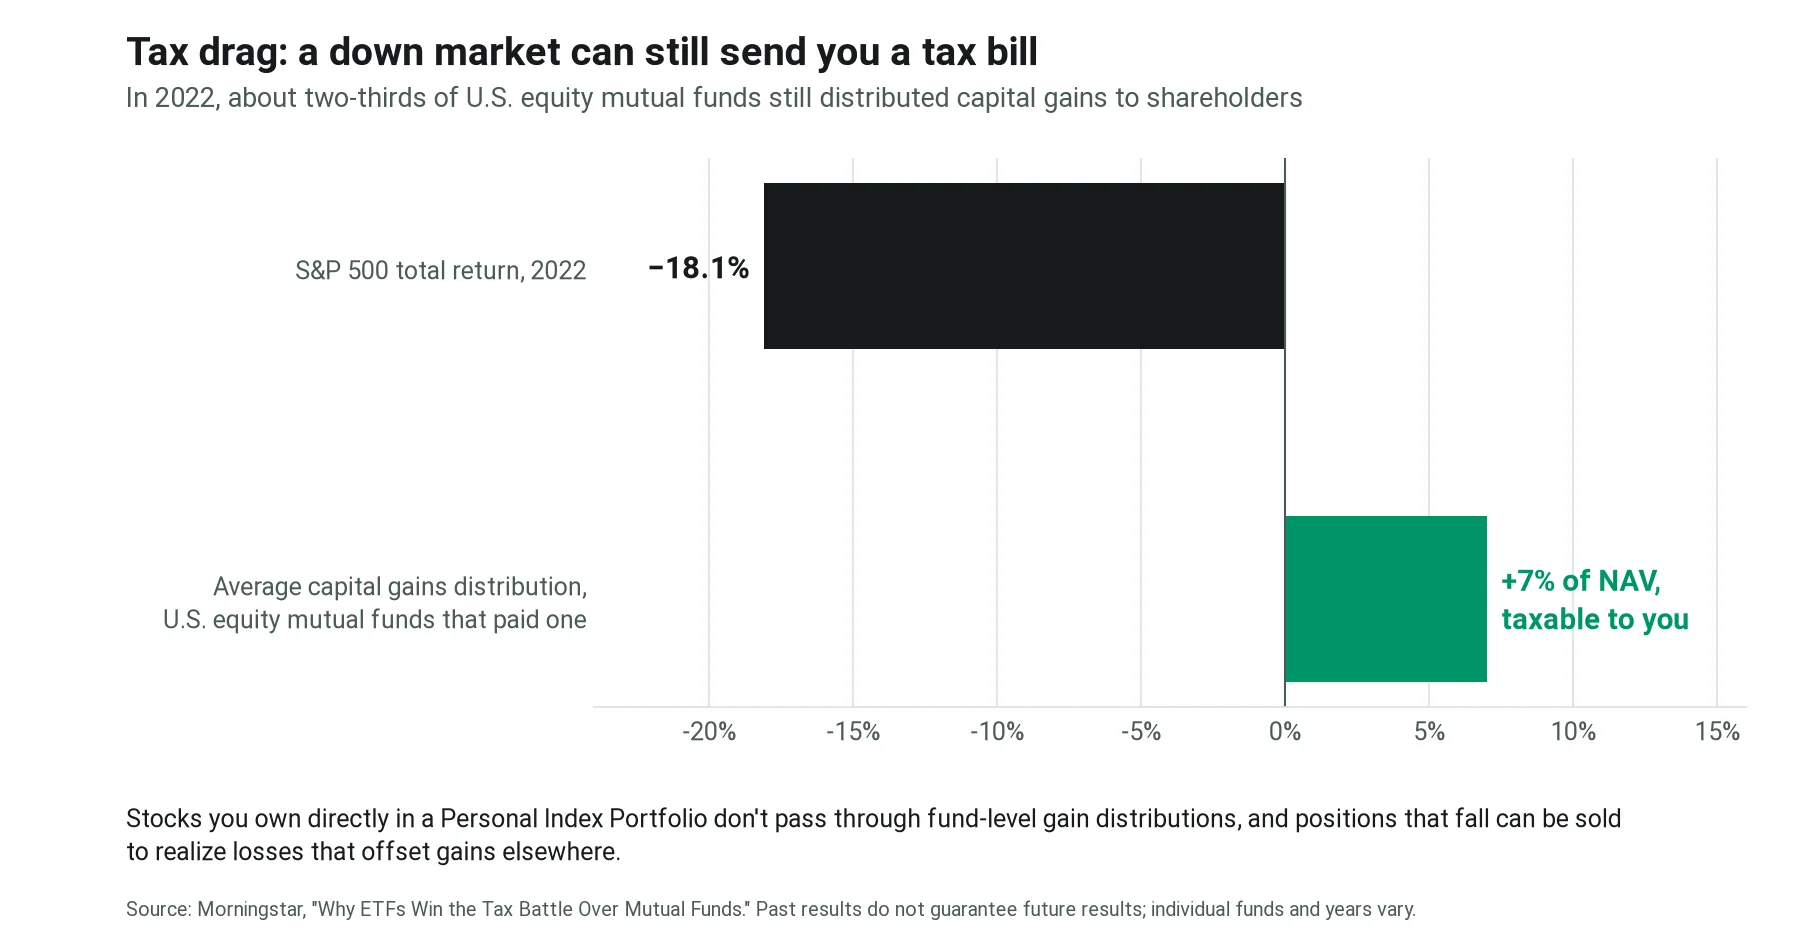
In retirement, keeping more of what you earn matters as much as the returns themselves. Traditional mutual funds can pass capital gains distributions to you at year-end, even in down markets. In 2022, the S&P 500 fell more than 18%, yet about two-thirds of U.S. equity mutual funds still distributed capital gains, averaging 7% of net asset value, according to Morningstar.
For finer control over taxes, we use Personal Index Portfolios. You hold individual stocks and index ETFs, so you own the underlying shares directly. In taxable accounts, this structure makes tax-loss harvesting possible: selling positions that have fallen to realize losses that offset gains elsewhere. That can add after-tax value, often called tax alpha, without giving up your asset allocation discipline. Active tax management is optional, applies to taxable accounts only, and is priced separately.
Aligning comprehensive planning with your life
Working with a fee-only fiduciary simplifies your financial picture so you can focus on your life goals. Comprehensive retirement income planning, portfolio management, and follow-through on our recommendations are included in our published advisory fee, with no separate planning charge.
Some executives also own separate businesses or need planning before an exit, such as QSBS planning or cash balance plan design. Those projects are led by Ryan Firth, CPA/PFS, and coordinated with your existing tax preparer. Tax planning for business owners is not included in the investment management fee. Each project is a custom engagement, priced and agreed separately before work starts. The project fee may be reduced by investment management fees you pay us.
Preparing for the distribution phase?
Your wealth is a tool to serve your life's goals. If you are preparing for retirement and want a specialized partner for the journey, take time to review how your portfolio is set up for the years ahead. Todd Smurl, CFA, manages portfolios for oil and gas professionals at Integrity Financial Planning, a fee-only fiduciary financial advisor in Houston. Schedule an introductory meeting to review your current portfolio, fees, and cash.
This article is for educational purposes only and is not individualized investment, tax, or legal advice. The fee chart is a hypothetical illustration, not a projection of any client account or investment. It assumes a constant 6% annual return before costs, no withdrawals or taxes, and total annual costs of 1.75% and 0.95%. Actual returns, costs, and tax results vary and are not guaranteed. Tax-loss harvesting does not eliminate taxes, and its value depends on market conditions and your tax situation. Full fee terms are in our Form ADV Part 2A.
Frequently asked questions
Why do executives switch from a brokerage firm to a fee-only fiduciary?
Usually because their needs change as they approach retirement. A fee-only fiduciary is paid only by clients, takes no commissions, and must act in the client's best interest. That model can reduce fee layers and gives one advisor responsibility for coordinating investments, taxes, and retirement income.
What does a fee-only fiduciary cost on a $3 million portfolio?
At Integrity Financial Planning, the fee is 1.0% per year on the first $1 million and 0.85% from $1 million to $10 million. On $3 million that works out to a blended 0.90%. Comprehensive financial planning is included, with no separate planning charge. See our fees.
Why do mutual funds create a tax bill in a down year?
When a mutual fund sells holdings at a gain, it must pass those gains to shareholders, who owe tax on them even if the fund lost value that year. In 2022, the S&P 500 fell more than 18%, yet about two-thirds of U.S. equity mutual funds still distributed capital gains, according to Morningstar.
Is tax-loss harvesting included in the advisory fee?
No. Active tax management, including daily tax-loss harvesting, is optional, applies to taxable accounts only, and carries a separate fee that we quote in writing. Clients who elect it receive an annual estimated Taxes Saved or Deferred report. See Personal Index Portfolios.
Get our insights by email
Occasional notes on planning, portfolios, and taxes. Unsubscribe anytime.
This article is for general educational purposes and is not individualized tax, legal, or investment advice. Tax laws change; confirm how current rules apply to your situation before acting. See our disclosures.